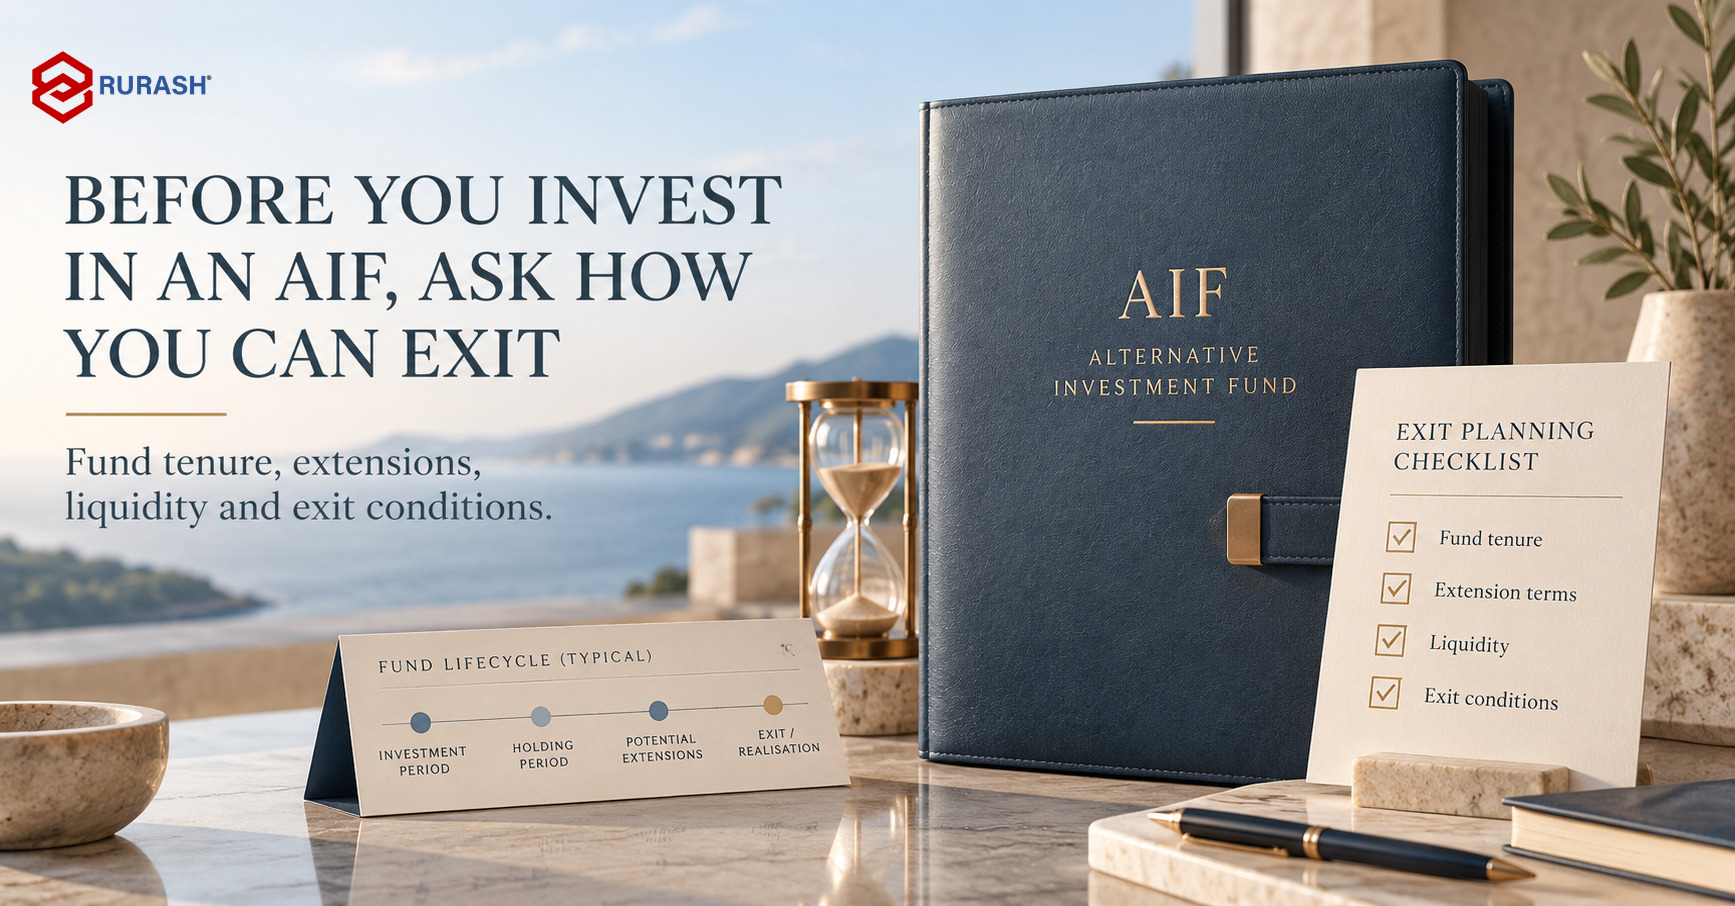
Hero insight: An attractive investment opportunity is only half the decision. Understanding when and how you can access your money is equally important.
Alternative Investment Funds (AIFs) have become an important investment avenue for High-Net-Worth Individuals (HNIs), Ultra-High-Net-Worth Individuals (UHNIs) and other eligible investors exploring opportunities beyond conventional investment products.
Depending on the fund’s strategy, AIFs may provide exposure to private equity, venture capital, private credit, real estate, listed securities and other alternative assets.
These opportunities can be compelling. However, they may also involve limited liquidity, extended investment periods and complex contractual arrangements.
An investor may spend considerable time evaluating a fund manager’s experience, investment strategy and projected returns.
Yet one of the most important questions can remain unanswered:
If you need your money before the investment matures, can you actually exit?
Understanding AIF exit conditions before committing capital can help investors avoid financial decisions that do not match their liquidity requirements.
Why Is an AIF Exit Strategy Important?
An exit strategy explains how an investor may eventually realise the value of an investment.
For conventional open-ended mutual funds, investors generally have access to redemption facilities, subject to the relevant scheme terms and regulatory restrictions.
AIFs can operate differently.
Certain AIFs invest in businesses or assets that do not have readily available buyers or actively traded secondary markets.
For example, a private equity fund may acquire a stake in an unlisted company and hold it for several years before seeking an exit through an IPO, strategic sale or other transaction.
The timing of that exit may depend on business performance, market conditions and the availability of suitable buyers.
Consequently, an investor’s capital may remain committed longer than originally expected.
A fund’s investment horizon and an investor’s personal liquidity requirements must be evaluated together.
1. Understand the AIF Category Before Investing
The first step is identifying the AIF category and its structure.
Under SEBI’s regulatory framework, AIFs are broadly classified into three categories.
AIF category | Typical investment focus | Liquidity consideration |
|---|---|---|
Category I | Venture capital, startups, infrastructure and other eligible sectors | Generally long-term, close-ended |
Category II | Private equity, private credit and other permitted strategies | Close-ended, often involving illiquid assets |
Category III | Strategies involving listed and other permitted securities, including certain complex trading approaches | May be open-ended or close-ended |
Category I and Category II AIFs are required to operate as close-ended funds and generally have a minimum tenure of three years.
Category III AIF schemes may be structured as either open-ended or close-ended.
This distinction directly affects how investors may access their capital.
However, even within the same category, exit arrangements can vary considerably.
Investors must examine the specific fund’s governing documents rather than relying only on its category.
2. What Does Fund Tenure Really Mean?
Fund tenure refers to the stated duration of a fund or scheme.
A Category II AIF, for example, may be structured with a seven-year tenure.
During the fund’s lifecycle, the manager may identify opportunities, deploy capital, manage investments and seek suitable exits.
Illustrative AIF investment lifecycle
01
Capital commitment
02
Investment and management
03
Exit planning
04
Realisation and distribution
But a seven-year tenure does not necessarily guarantee that every underlying asset will be sold and every investor will receive the full expected proceeds exactly at the end of seven years.
Market conditions, investment performance and exit opportunities may affect the timing and value of distributions.
Investors should therefore distinguish between the fund’s stated tenure and the actual timing of cash returns.
3. Can an AIF Extend Its Tenure?
Yes. Close-ended AIFs may be permitted to extend their tenure under applicable SEBI regulations and scheme-specific conditions.
The general regulatory framework permits extensions of up to two years with approval from at least two-thirds of unit holders by value of their investment, subject to applicable provisions.
There are also special frameworks for certain eligible funds, including large-value funds for accredited investors. The precise rules need to be checked for the relevant scheme.
Consider a hypothetical AIF with a seven-year initial tenure.
If an extension is approved in accordance with the applicable rules, investors may remain invested beyond the original timeline.
This could happen because the fund needs additional time to realise underlying assets.
For an investor expecting to use the proceeds for a financial commitment immediately after seven years, the extension could create a liquidity challenge.
Before investing, understand how extensions are approved, whether your consent is individually required and what happens if you disagree with an extension.
An extension provision is not simply a regulatory technicality. It can materially affect your financial planning.
4. Can Investors Withdraw Money Before an AIF Matures?
This depends on the scheme’s structure.
In close-ended AIFs, investors generally should not assume that they have an ordinary redemption facility during the fund’s tenure.
Some schemes may permit transfers of units, subject to fund-document restrictions, applicable rules and other requirements.
However, transferability does not automatically mean liquidity.
Even if a transfer is permitted, the investor may not find an eligible buyer at the desired time or price.
Open-ended Category III AIFs may offer periodic redemptions, but these are subject to scheme-level terms.
SEBI’s framework also addresses liquidity management and allows for the possibility of redemption suspension in exceptional circumstances, subject to applicable requirements and disclosures.
Investors should review notice periods, redemption dates, lock-ins, charges and any restrictions before making an allocation.
5. What Happens If the Fund Cannot Sell Its Investments?
An AIF may reach the end of its planned tenure while still holding investments that cannot be realised promptly.
This can happen where portfolio companies remain unlisted, private-market valuations are uncertain or suitable buyers are unavailable.
SEBI has established frameworks dealing with liquidation, winding up, unliquidated investments and related processes.
In June 2026, SEBI also issued guidelines addressing retention of proceeds and the treatment of certain funds as inoperative during winding-up arrangements.
These regulatory processes do not guarantee an immediate or full return of investor capital.
Depending on the scheme and circumstances, investors may face delayed distributions, reduced realisations or other consequences described in the governing documents and applicable regulations.
Understanding the worst-case liquidity scenario is as important as understanding the expected investment outcome.
6. Understand Capital Calls and Drawdown Obligations
Many AIFs use a commitment-based investment structure.
Instead of contributing the entire committed amount on the first day, an investor may be asked to contribute capital through drawdowns over time.
For example, an investor could make a hypothetical commitment of ₹1 crore to an AIF.
The fund may initially call ₹25 lakh and request additional contributions later, according to its terms.
This means the investor must plan for future financial obligations even after making the initial investment.
Failure to honour a drawdown notice can trigger contractual consequences, potentially including penalties or other remedies.
Therefore, AIF liquidity planning should address both directions of cash flow: when the investor must contribute capital and when distributions may become available.
7. Know the Difference Between Valuation and Realised Returns
AIFs may report periodic portfolio valuations or net asset values.
However, a reported gain is not necessarily an amount an investor can immediately withdraw.
An unlisted company’s valuation may increase while the AIF continues holding the investment.
Until the position is realised and distributable proceeds become available, the investor may not receive cash corresponding to that valuation.
Furthermore, actual distributions can be affected by fees, expenses, losses on other investments and the fund’s distribution waterfall.
Paper valuations and cash received are two different measures of investment outcomes.
This is especially important when comparing alternative investments with more liquid financial products.
8. Understand Fees, Expenses and Exit-Related Costs
Investors should review the complete fee structure of an AIF.
Depending on the fund, this may include management fees, performance-related fees or carried interest, administrative expenses and other charges.
Fees may be calculated on different bases over the investment lifecycle.
The fund’s distribution waterfall can also affect the amount and timing of proceeds investors receive.
If early transfers or redemptions are permitted, additional costs or conditions may apply.
Tax consequences should also be evaluated according to the fund’s structure and the investor’s circumstances.
The relevant Private Placement Memorandum (PPM), contribution agreement and other governing documents should be examined carefully.
9. How Does AIF Liquidity Affect Portfolio Allocation?
An investment may offer attractive opportunities but still be unsuitable if it ties up money needed for other financial commitments.
Consider two hypothetical investors.
Investor A has diversified financial assets, adequate emergency reserves and no major anticipated liquidity requirement during the proposed AIF’s term.
Investor B expects to need a substantial part of the investment amount for a business expansion in three years.
Both investors may be considering the same seven-year close-ended AIF.
However, their ability to tolerate illiquidity may differ considerably.
This illustrates an important principle:
A suitable investment must match both the investor’s return objectives and the timing of their financial needs.
There is no universal percentage of an investor’s portfolio that should be allocated to illiquid AIFs.
The decision depends on total assets, liabilities, recurring income, existing alternative investments and the capacity to withstand delayed capital returns.
AIF Exit Checklist: What Should Investors Ask?
Checkpoint | Question before investing |
|---|---|
Fund structure | Is the scheme open-ended or close-ended? |
Tenure | When is the scheduled maturity? |
Extension | Can the tenure be extended, and how is approval obtained? |
Redemption | Are withdrawals permitted during the fund’s lifecycle? |
Transfer | Can units be sold or transferred, and under what conditions? |
Capital commitment | How much money must be contributed later? |
Underlying assets | How liquid are the fund’s investments? |
Exit strategy | How does the manager intend to realise investments? |
Distribution | When and how may proceeds be distributed? |
Winding up | What happens if assets remain unsold? |
Costs | What charges and taxes may affect investor proceeds? |
This checklist should be considered alongside the fund manager’s investment process, track record, risk management and the investor’s overall financial position.
What Documents Should You Read Before Investing?
The most important starting point is the fund’s PPM, together with the contribution agreement and other applicable governing documents.
These documents explain the investment mandate, risk factors, tenure, distribution terms, redemption or transfer provisions and investor obligations.
The PPM should not be treated simply as an administrative formality.
It contains information that can materially affect an investor’s rights, liquidity and financial exposure.
Before committing capital, investors should request clarification on any term they do not understand.
Ranjit Jha’s Perspective — Draft for Approval
Proposed editorial perspective for Ranjit M. Jha, MD & CEO, Rurash Financials. Approval required before attribution.
Alternative Investment Funds can offer access to specialised strategies that differ considerably from conventional investments.
However, an investor should evaluate an AIF not only through its investment thesis and potential returns, but also through its liquidity structure.
Fund tenure, extension provisions, capital-call obligations and exit mechanisms can significantly influence the investor’s overall financial position.
A thoughtful allocation to alternative investments begins with understanding how long capital may remain committed and whether that timeline is compatible with the investor’s broader financial responsibilities.
Explore More with Rurash
At Rurash Financials, we believe alternative-investment decisions should be supported by careful evaluation of risk, strategy, liquidity and portfolio suitability.
For HNIs, UHNIs and eligible investors exploring AIF opportunities, understanding fund tenure and exit arrangements is an important part of the investment process.
Through our AIF and wealth management offerings, investors can explore strategies while reviewing their financial objectives, capital commitments and liquidity requirements.
Before investing in an AIF, understand how—and when—you may exit.