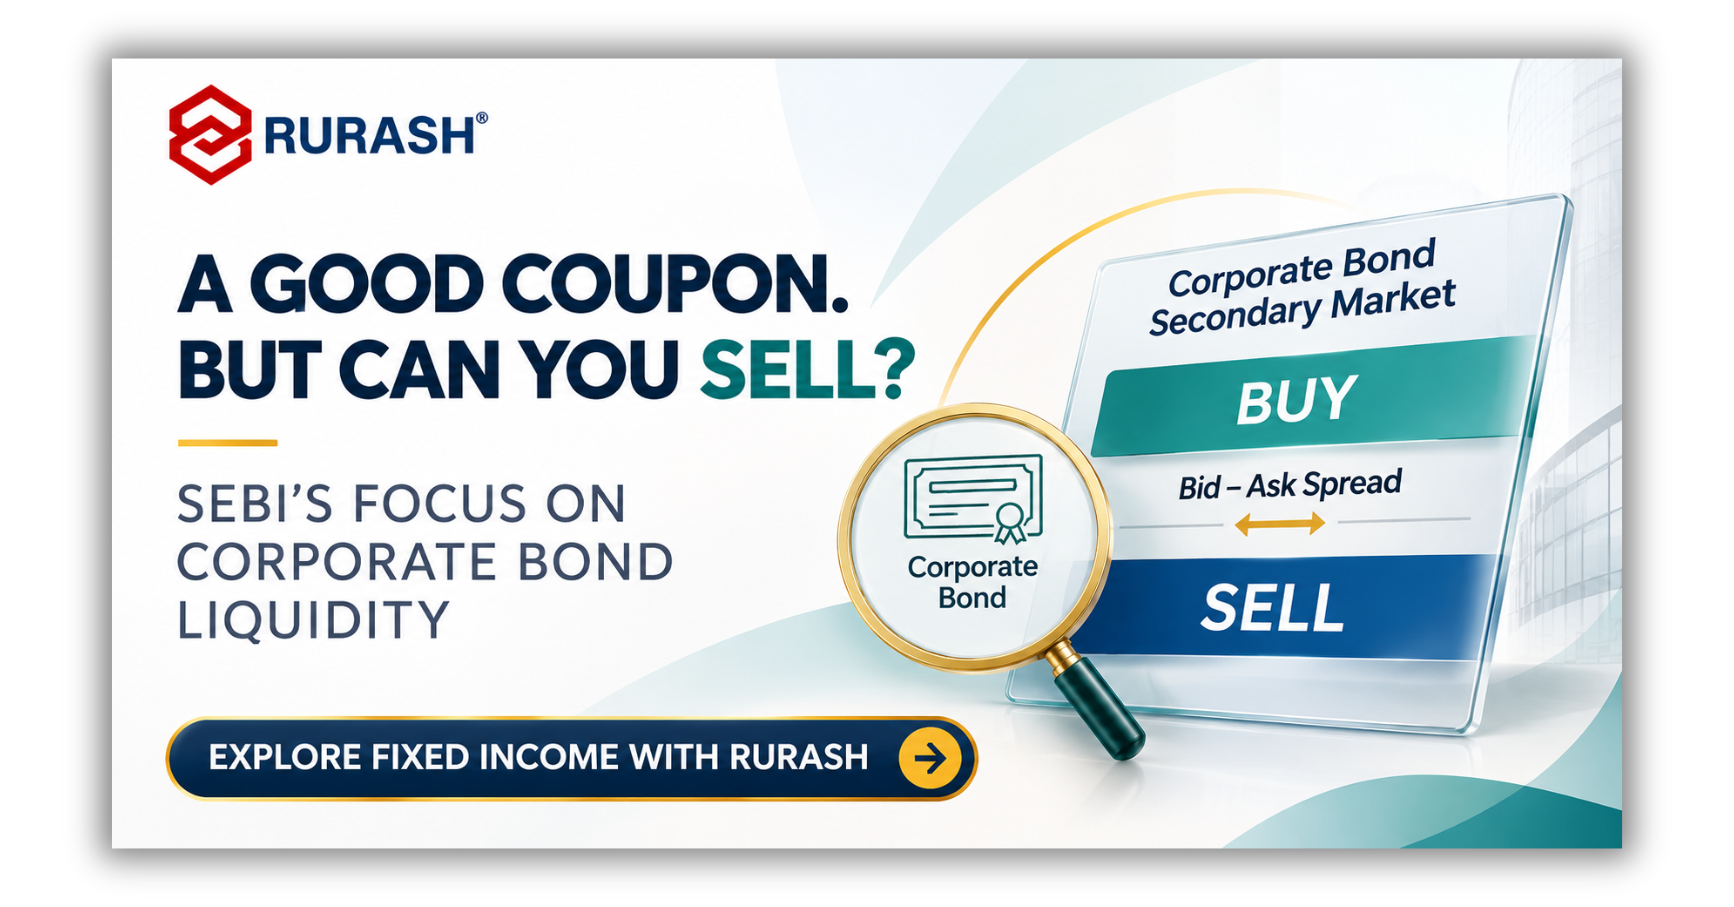
A corporate bond may offer an attractive coupon. But what happens if you need to sell it before maturity?
Corporate bonds can provide investors with a source of periodic interest income while allowing companies to raise capital beyond traditional bank loans.
For investors seeking to diversify beyond equities and fixed deposits, corporate bonds may offer opportunities across different issuers, maturities, credit ratings and interest-payment structures.
However, an important aspect of bond investing often receives less attention than the advertised coupon.
Liquidity.
A bond may promise regular interest payments and principal repayment at maturity. But if an investor needs to exit earlier, finding a buyer at a reasonable price can be difficult.
This challenge has become a priority for the Securities and Exchange Board of India .
On 19 November 2026, SEBI Whole-Time Member K. V. R. Murty discussed the regulator’s work on a market-making framework intended to improve secondary-market liquidity in corporate bonds. On 20 November, additional reporting described SEBI’s coordination with the Reserve Bank of India (RBI) and Finance Ministry on the same broader objective.
The development highlights a fundamental question.
Can India’s corporate bond market become more accessible, actively traded and transparent without weakening investor protection?
For investors, understanding the answer begins with recognising the difference between a bond’s contractual income and its ability to be sold.
What Happened? SEBI Is Working to Improve Bond Market Liquidity
SEBI has been developing measures to deepen India’s corporate bond market, including improvements in secondary trading, price discovery and market-making arrangements.
The latest November discussions are part of a longer regulatory effort.
The proposed market-making framework is intended to encourage intermediaries to provide more consistent opportunities to buy and sell eligible corporate bonds.
Market makers may help improve trading activity by offering buying and selling quotations, subject to whatever obligations and safeguards SEBI ultimately adopts.
The regulator is also working with other financial authorities because India’s corporate bond market involves banks, mutual funds, insurers, clearing institutions and other participants.
Importantly, the market-making framework being discussed should not be presented as a newly implemented, universal liquidity guarantee.
The final obligations, eligible securities and implementation conditions need to be established through the applicable regulatory process.
1. What Does Liquidity Mean in Corporate Bonds?
Liquidity refers to how easily an investor can buy or sell a security without significantly affecting its price.
In the equity market, heavily traded shares may attract numerous buyers and sellers throughout the trading session.
Corporate bonds often operate differently.
Some highly rated bonds issued by large companies may attract regular institutional interest.
Others may trade infrequently, even when the issuer continues meeting its interest obligations.
This means an investor’s ability to sell depends on the specific security, buyer demand, prevailing yields and market conditions.
A bond can be financially sound but still difficult to sell quickly.
For example, an investor holding a five-year corporate bond may want to sell after two years to meet a family expense.
If buyers are limited, the investor might need to accept a lower price or wait for a suitable counterparty.
Credit quality and liquidity are separate investment considerations.
2. Why Does SEBI Consider Liquidity a Structural Challenge?
India’s corporate debt market has grown, but secondary-market trading remains uneven.
In May 2026, SEBI Whole-Time Member Amarjeet Singh highlighted that India’s corporate bond market was approximately 16% of GDP and that secondary-market turnover remained relatively low compared with selected Asian economies.
He cited an annual turnover ratio of approximately 0.3 for India, against 1.17 for Indonesia and 1.16 for China.
The same remarks noted that issuance was concentrated among highly rated securities and large issuers, while retail participation remained limited.
CORPORATE BOND SECONDARY-MARKET TURNOVER
Figures cited in SEBI Whole-Time Member Amarjeet Singh’s May 2026 remarks. These are historical comparative measures, not real-time November 2026 turnover ratios.
A lower turnover ratio suggests that a smaller proportion of outstanding bonds changes hands over a given period.
This does not mean that every Indian corporate bond is illiquid.
It indicates that the market as a whole has room to develop more frequent and deeper secondary trading.
3. Why Does the Secondary Market Matter?
The primary market is where companies issue new bonds to raise capital.
The secondary market is where investors trade bonds that have already been issued.
For example, an investor may subscribe to a three-year bond during its public issue.
A year later, that investor may want to sell the bond to someone else.
The transaction takes place in the secondary market, subject to the bond’s listing and trading arrangements.
A functioning secondary market benefits both buyers and sellers.
Investors may gain greater flexibility to change their holdings, while reliable trading prices can help other participants assess the value of similar securities.
Companies may also benefit indirectly.
If investors believe they will have reasonable opportunities to exit, they may be more willing to consider new debt issues.
Over time, this can support broader market participation and financing alternatives for businesses.
4. What Is Market Making?
Market making is an arrangement under which designated participants provide quotations for buying and selling securities, subject to applicable rules.
In a bond market, these participants can help connect investors who want to sell with those who want to buy.
A market maker may quote a bid price and an ask price.
The bid is the price at which a buyer is willing to purchase the security.
The ask is the price at which a seller is willing to offer it.
The difference is called the bid-ask spread.
A narrower spread can reduce the transaction cost of buying or selling.
However, the availability of quotations, the maximum trading quantity and market-maker obligations depend on the final framework and market conditions.
Market making is intended to support liquidity, not eliminate price risk or guarantee an investor’s original purchase value.
5. Why Does the Bid-Ask Spread Matter?
The bid-ask spread is particularly important for investors who may sell before maturity.
Consider a hypothetical bond with a face value of ₹1,000.
Suppose the market displays an indicative buying price of ₹980 and a selling price of ₹990.
An investor seeking to sell immediately may receive approximately ₹980 per bond before applicable transaction charges.
Another investor purchasing at the same time may pay around ₹990.
The difference reflects part of the cost associated with market execution.
In less liquid securities, quoted spreads may be wider.
The example below is illustrative.
| Market condition | Illustrative bid | Illustrative ask | Spread |
|---|---|---|---|
| More actively traded bond | ₹995 | ₹999 | ₹4 |
| Less actively traded bond | ₹970 | ₹990 | ₹20 |
These are not actual market quotations.
They demonstrate why two bonds offering similar coupons may involve different transaction costs.
An investor should therefore consider both yield and the practical cost of entering or exiting a position.
6. Why Does a Higher Coupon Not Guarantee a Better Exit?
The coupon is the interest payment specified in the bond’s contractual terms.
The market price is what investors may be willing to pay for the security at a particular point in time.
These are not the same.
For example, suppose an investor purchases a bond with an annual coupon of 9%.
Later, market interest rates rise and comparable new bonds offer higher yields.
The existing bond’s market price may decline to make its remaining cash flows more competitive with newer issues.
Credit developments can also affect the price.
If the issuer’s financial condition deteriorates, investors may demand a higher yield, pushing down the price they are willing to pay.
Limited liquidity may compound these effects.
The interest promised by a bond does not establish the price at which it can be sold before maturity.
7. What Has SEBI Already Done to Improve Bond Trading?
SEBI has introduced several mechanisms over recent years to strengthen debt-market participation and infrastructure.
These include the Request for Quote (RFQ) platform, Online Bond Platform Providers (OBPPs), improvements in debt-security disclosures and corporate bond repo arrangements.
The RFQ platform provides an electronic mechanism through which market participants can request and respond to trading quotations.
SEBI’s Annual Report 2025–26 recorded significant growth in RFQ activity.
Average monthly RFQ trading turnover rose from approximately ₹44,096 crore in FY2024–25 to ₹60,985 crore in FY2025–26.
RFQ PLATFORM — AVERAGE MONTHLY TRADED VALUE
Source: SEBI Annual Report 2025–26. Annual financial-year averages, not current-month trading data.
This represents progress in electronic trading activity.
But greater aggregate trading volume does not necessarily mean that every individual corporate bond has become liquid.
Trading can remain concentrated in particular issuers, maturities and credit categories.
8. What Role Could Corporate Bond Repos Play?
Repo transactions allow eligible securities to be used in short-term funding arrangements under specified conditions.
Corporate bond repo mechanisms can help financial institutions manage liquidity using eligible debt securities.
India’s Limited Purpose Clearing Corporation framework, operating through AMC Repo Clearing Limited, is part of this market infrastructure.
SEBI’s Annual Report 2025–26 showed that average monthly corporate debt repo trading volume through the relevant platform increased from approximately ₹24,817 crore in FY2024–25 to ₹63,893 crore in FY2025–26.
A more developed repo market may help financial intermediaries finance bond inventories and support trading activity.
However, repo financing has its own collateral, valuation and counterparty-risk considerations.
It should not be confused with a retail investor’s automatic right to sell a bond at a particular price.
9. How Could Better Liquidity Benefit Retail Investors?
For retail investors, a more actively traded bond market could make it easier to compare quotations and evaluate available exit options.
A deeper secondary market may also improve transparency and help investors understand how bond prices respond to interest rates and credit conditions.
However, several limitations remain.
Retail investors may still encounter minimum trading quantities, brokerage or platform charges, varying market depth and limited interest in particular bonds.
Therefore, investors should not assume that a bond is readily saleable simply because it is listed or available through an online platform.
Before purchasing, it is useful to check actual recent trading activity and the available market quotations.
10. What Does This Mean for Debt Mutual Funds?
Debt mutual funds may hold corporate bonds as part of their portfolios.
For a debt fund, the liquidity of underlying investments matters when managing subscriptions, redemptions and portfolio changes.
If a fund needs to sell securities, weak trading conditions can affect execution prices.
More developed secondary trading could help fund managers execute transactions and manage liquidity more efficiently.
However, improved bond-market infrastructure does not guarantee higher debt fund returns.
Debt mutual funds remain exposed to changes in interest rates, credit quality and the market value of their holdings.
Investors should evaluate the fund’s portfolio, credit profile, duration, liquidity and expenses rather than relying solely on the expectation of regulatory improvements.
11. Can Better Liquidity Reduce Borrowing Costs for Companies?
Potentially, although the outcome is not automatic.
A company issuing bonds must attract investors willing to provide capital at an acceptable yield.
If investors expect difficulty selling the bonds later, they may demand additional compensation for that liquidity risk.
A more liquid market may reduce some of that required compensation.
This could improve borrowing conditions for certain issuers over time.
However, the issuer’s creditworthiness, financial performance, maturity profile and market interest rates remain important.
A company with weak fundamentals may still face high borrowing costs even in a more liquid market.
The benefit of liquidity improvements will therefore differ across issuers and securities.
12. Why Investors Should Check Credit Quality Separately
Liquidity and credit risk are often discussed together, but they are distinct.
Credit risk concerns the possibility that an issuer may fail to meet its payment obligations.
Liquidity risk concerns the difficulty of selling a security at a reasonable price when needed.
A bond can be highly rated yet trade infrequently.
A bond can also be actively traded while carrying substantial credit risk.
Credit ratings may help investors assess an issuer’s debt-servicing capacity, but they are not guarantees.
Investors should examine the rating rationale, company financial statements, security arrangements, repayment obligations and relevant covenants.
Improving market liquidity does not remove the risk of default or capital loss.
13. What Should Senior Citizens and HNIs Consider?
Senior citizens often evaluate bonds for periodic income and the preservation of savings.
HNIs may use bonds to diversify large portfolios or plan future cash requirements.
In both cases, investors should establish whether they are likely to require their money before the bond matures.
A bond offering an attractive coupon but limited secondary trading may be less suitable for someone expecting significant near-term expenses.
Similarly, a long-duration bond can experience meaningful market-price fluctuations when yields change.
For investors holding several bonds, concentration in one issuer or sector can introduce additional risks.
The investment decision should therefore consider income requirements, maturity, credit quality and liquidity together.
Corporate Bond Liquidity Checklist
Before investing, review the following:
| What to check | Why it matters |
|---|---|
| Coupon rate | Shows contractual interest payments |
| Yield to maturity | Helps evaluate expected return at the actual purchase price, assuming promised payments occur |
| Credit rating and rationale | Provides information about credit risk |
| Maturity date | Determines the scheduled repayment horizon |
| Recent trading activity | Helps assess secondary-market participation |
| Bid-ask spread | Indicates potential transaction costs |
| Issue size and outstanding amount | Provides context about the security’s market depth |
| Security and covenants | Helps assess contractual creditor protections |
| Tax treatment | Affects post-tax investment outcomes |
| Personal liquidity needs | Determines whether the holding period is realistic |
What Should Investors Watch Next?
The November 2026 discussions indicate that SEBI continues to prioritise the development of corporate bond market-making arrangements.
Investors should monitor whether the regulator issues a formal consultation paper or circular specifying market-maker eligibility, quoting requirements, eligible bonds and implementation timelines.
The practical effects should then be assessed through trading volumes, quoted spreads, execution quality and participation across different bond categories.
Until these arrangements are finalised and implemented, investors should evaluate liquidity using the market conditions currently available.
Ranjit Jha’s Perspective — Draft for Approval
Proposed editorial perspective for Ranjit M. Jha, MD & CEO, Rurash Financials. Approval required before attribution.
India’s corporate bond market has an important role in financing businesses and providing investment opportunities beyond traditional deposits and listed equities.
However, developing a deeper market requires more than increasing the number of bond issuances.
Secondary-market liquidity, transparent price discovery and greater investor participation are important for improving confidence in the asset class.
SEBI’s continued focus on market-making arrangements reflects these structural requirements.
For investors, the key is to assess both the contractual income from a bond and the practical ability to exit before maturity.
Credit quality, valuation, liquidity and investment horizon should remain central to every fixed-income decision.
The Bigger Picture: A Strong Bond Market Needs More Than New Issuances
India’s corporate bond market has developed significantly over time, supported by improvements in market infrastructure and electronic trading.
Yet liquidity remains uneven across different securities and issuers.
SEBI’s latest focus on market making reflects the need to strengthen the secondary market alongside the primary market.
A more active secondary market could support better price discovery, wider investor participation and more efficient financing.
However, the benefits will depend on the design and actual implementation of the framework.
For investors, the most important lesson is that a bond’s attractiveness depends not only on the interest it pays but also on the risks and costs associated with holding or selling it.
Explore More with Rurash
At Rurash Financials, we believe fixed-income investment decisions should begin with a clear understanding of yield, creditworthiness, liquidity and investment horizon.
For retail investors, senior citizens, HNIs and business owners considering corporate bonds, these factors can help determine whether a security fits their financial objectives.
Through Rurash’s Fixed Income services, eligible investors can explore bond opportunities while considering income requirements, market conditions and portfolio diversification.
A higher coupon may attract attention. Understanding liquidity can make the investment decision more informed.
Connect With Rurash Financials
Connect with Rurash Financials Pvt. Ltd. to discuss how corporate bond market liquidity, credit quality and changing bond yields can affect your fixed-income allocation.