Hook: A change in how mutual funds settle trades may not be visible in your portfolio, but it matters to how funds operate.
When investors evaluate a mutual fund, they usually focus on returns, expense ratios, asset allocation, investment strategy and the experience of the fund manager.
However, there is another important part of mutual fund operations that rarely receives investor attention: how securities transactions are settled.
Every time a mutual fund scheme purchases or sells shares through the cash market, the transaction creates obligations involving money and securities.
These obligations must be completed through the market’s settlement infrastructure.
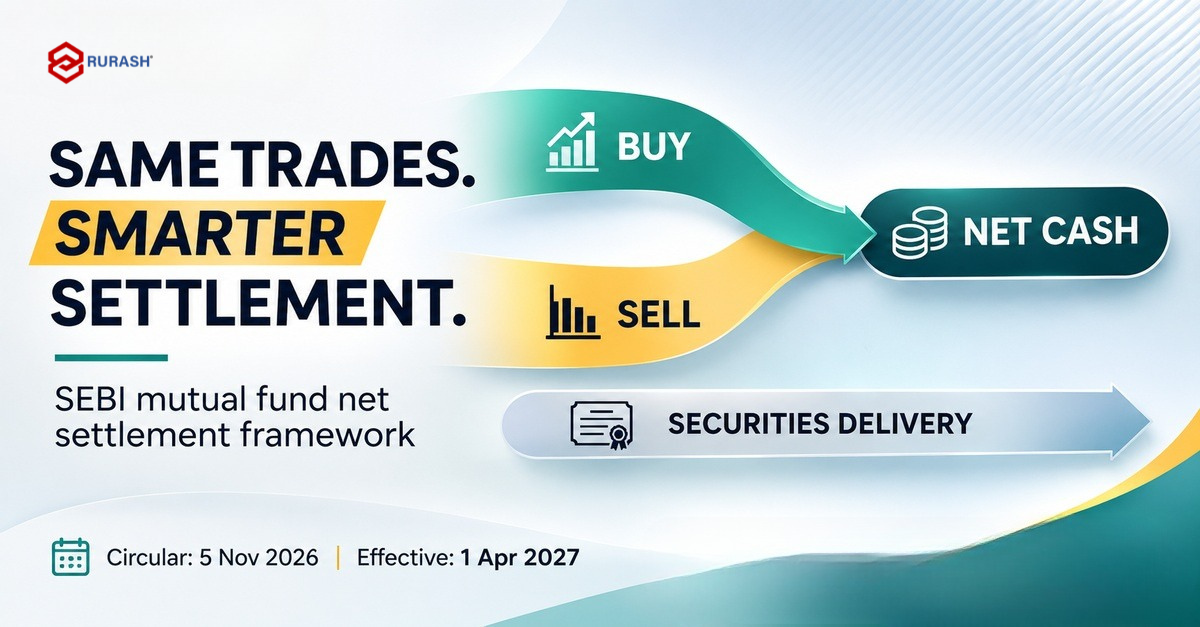
On 5 November 2026, the Securities and Exchange Board of India (SEBI) introduced a framework allowing eligible cash-market transactions undertaken by mutual fund schemes to benefit from net settlement of funds.
The objective is to reduce temporary funding requirements and improve settlement efficiency.
The change does not alter the fundamental investment strategy of a mutual fund or guarantee better investment returns. It changes how qualifying trade-related cash obligations can be managed.
For investors, understanding the distinction between operational efficiency and investment performance is important.
What Happened? SEBI Introduced a New Mutual Fund Settlement Framework
SEBI issued its circular titled Framework for net settlement of funds for transactions undertaken by mutual fund schemes in cash market on 5 November 2026.
Under the framework, qualifying outright purchases and sales can be offset for cash-settlement purposes within an individual mutual fund scheme and the same settlement cycle.
The transfer of the actual securities continues on a gross basis.
The rules are scheduled to come into force on 1 April 2027, giving market participants time to prepare their systems and procedures.
This distinction is important because the framework is not a permission for unrestricted netting across every trade or every scheme managed by an asset management company.
It is a defined operational arrangement with eligibility conditions and safeguards.
1. What Is Gross Settlement in Mutual Funds?
Under gross settlement, the eligible purchase and sale obligations are handled separately rather than being offset against one another at the individual scheme level.
When a mutual fund scheme purchases securities, funds must be available to complete the purchase obligation.
When it sells securities, the corresponding sale proceeds are received through the settlement process.
For example, a scheme purchasing securities worth ₹10 crore and selling other securities worth ₹7 crore may have separate purchase and sale cash obligations.
The fund needs to manage the timing and availability of cash required for settlement, even when it expects sale proceeds during the same cycle.
This can create temporary funding requirements.
Importantly, gross settlement is not necessarily an indication of inefficiency or risk. It is an established method of completing transactions.
2. How Does Net Settlement Work?
Net settlement allows qualifying payment obligations to be offset within the permitted settlement framework.
Instead of separately funding the entire eligible purchase obligation, the scheme may settle the residual cash amount after considering eligible sales.
Consider this simplified example:
ILLUSTRATIVE NET SETTLEMENT
Eligible purchases
₹10 Cr
Eligible sales
₹7 Cr
Residual cash payment after eligible netting
₹3 Cr
₹10 crore − ₹7 crore = ₹3 crore
Hypothetical illustration assuming all shown transactions are outright, eligible, within one scheme and the same settlement cycle. Actual obligations depend on the circular’s exclusions and settlement rules.
The scheme still purchases ₹10 crore worth of securities and sells ₹7 crore worth of securities.
The transactions themselves do not disappear.
Only the qualifying cash obligations are offset for settlement purposes.
Net settlement changes the movement of money required for eligible trades. It does not cancel the underlying investments.
3. Which Mutual Fund Transactions Qualify?
SEBI has introduced specific conditions.
An outright transaction means a purchase or a sale in a particular security, but not both, within the same settlement cycle for the mutual fund scheme.
For example, if the scheme buys shares of Company A and sells shares of Company B, those transactions may qualify for cash netting, assuming the other requirements are met.
However, if the scheme both buys and sells Company A shares during the same settlement cycle, those transactions in Company A are treated as non-outright and excluded from the permitted netting.
Non-outright purchase obligations must continue to be funded separately.
The framework also excludes transactions such as derivatives, securities lending and borrowing, and short-sale-related transactions.
This prevents investors from interpreting the circular as unrestricted permission to offset all market transactions.
4. Why Is Scheme-Level Netting Important?
A mutual fund house may manage several schemes.
These could include large-cap funds, flexi-cap funds, sectoral funds and other investment products.
Each scheme maintains its own assets, liabilities, accounting and investment mandate.
SEBI’s circular permits eligible netting only within the same mutual fund scheme and settlement cycle.
It does not permit one scheme’s sale proceeds to be used to offset another scheme’s purchase obligations under the new mechanism.
This protects the separation of scheme-level obligations.
It also helps preserve the accounting and investment boundaries that matter to unit holders.
5. Does Securities Settlement Also Become Net-Based?
No.
One of the most important features of the circular is that securities settlement continues on a gross basis.
The securities purchased or sold must still be delivered through the applicable settlement mechanism.
Securities Transaction Tax and stamp duty also continue to apply on the relevant delivery basis.
The framework does not change the delivery-backed nature of institutional trades.
In other words, the reform concerns eligible cash settlement, not the elimination of securities delivery.
6. Why Can Net Settlement Improve Operational Efficiency?
Mutual fund schemes regularly purchase and sell securities as part of portfolio management.
Cash may be required for purchases before corresponding sales proceeds are fully available through the relevant settlement arrangements.
By reducing the need to fund both sides of qualifying transactions separately, net settlement can reduce temporary cash requirements.
This may help schemes manage operational liquidity more efficiently.
It could also reduce certain settlement-related funding frictions, depending on the circumstances.
However, the actual operational benefit will vary with a scheme’s trading activity, transaction eligibility, systems and other factors.
A fund making few qualifying offsetting transactions may experience less benefit than a fund with substantial eligible buying and selling within the same settlement cycle.
7. What Does Not Change for Retail Mutual Fund Investors?
For retail investors, the reform is primarily operational rather than a change in the investment product itself.
The circular does not directly change a scheme’s investment objective, asset-allocation mandate, unit ownership or published fee structure.
It also does not automatically change the usual investor-facing subscription and redemption arrangements.
Importantly, the scheme’s Net Asset Value (NAV) must continue to be calculated according to the applicable valuation and accounting rules.
SEBI specifically requires the netting mechanism not to affect scheme-wise NAV computation, investment limits, accounting, asset allocation or unit-holder interests.
Investors should therefore distinguish this change from reforms concerning expense ratios, fund categorisation or redemption rules.
8. Will Net Settlement Lead to Higher Mutual Fund Returns?
Not necessarily.
Operational efficiency and investment performance are related but different concepts.
Investment returns primarily depend on the performance of the underlying assets, the manager’s decisions, market movements and expenses.
A more efficient settlement mechanism may reduce certain temporary funding requirements, but that does not establish a predictable improvement in NAV or investor returns.
The circular also does not announce a mandatory reduction in mutual fund expense ratios.
Any cost benefits would need to be evaluated through actual implementation and scheme-level outcomes.
Investors should not choose a mutual fund merely because the new settlement mechanism is available.
9. What Responsibilities Do AMCs and Custodians Have?
The new arrangement requires coordination across asset management companies, custodians, brokers, clearing corporations and recognised stock exchanges.
AMCs and custodians must identify eligible and excluded transactions correctly.
They must maintain separate records of gross cash obligations, net cash obligations and securities delivery.
Custodians are required to maintain an appropriate audit trail.
Trustees must review implementation to ensure that the arrangement protects unit-holder interests.
AMFI will develop detailed implementation standards in consultation with the relevant market institutions.
These operational safeguards are essential because reducing cash requirements must not weaken scheme accounting or settlement discipline.
10. What Should Mutual Fund Investors Focus On?
The November settlement framework is useful to understand, but it should not replace the core considerations involved in mutual fund selection.
Investors should continue examining the scheme’s objective, asset allocation, investment strategy, costs, riskometer, liquidity and suitability.
A fund’s investment performance should be evaluated over relevant periods and compared with appropriate benchmarks.
Portfolio overlap, concentration and the investor’s own time horizon also remain important.
Operational improvements can strengthen market infrastructure, but they are only one part of the mutual fund investment process.
Ranjit Jha’s Perspective — Draft for Approval
Proposed editorial perspective for Ranjit M. Jha, MD & CEO, Rurash Financials. Approval required before attribution.
SEBI’s net-settlement framework reflects the importance of strengthening the operational infrastructure supporting India’s mutual fund industry.
Allowing eligible scheme-level cash obligations to be offset may help reduce temporary funding requirements while maintaining the safeguards necessary for securities settlement.
For investors, however, greater operational efficiency should not be confused with assured investment performance.
Mutual fund decisions should continue to be based on asset allocation, risk, cost, investment objectives and portfolio suitability.
A more efficient market structure is a positive operational development, but disciplined investment planning remains essential.
Explore More with Rurash
At Rurash Financials, we believe understanding regulatory developments can help investors make more informed decisions about financial products.
Through our mutual fund and wealth management services, eligible investors can explore scheme selection, asset allocation, diversification and goal-based investing.
Better settlement efficiency supports fund operations. Better investment decisions begin with a clear financial plan.
Explore Mutual Fund Investment Planning with Rurash Financials